Tag: ANAROCK Group

Housing Sales Taper in Q2 2024 in Top 7 Cities – 8% Q-o-Q Fall, up 5% Y-o-Y

Mumbai 27 June 2024: The bull run in residential sales across the top 7 cities tamed down marginally in the second quarter of 2024, to the backdrop of increasing property prices and a high base record of the previous quarter (Q1 2024). Latest ANAROCK Research data reveals that housing sales witnessed a quarterly drop of 8% and stood at approx. 1,20,340 units in Q2 2024 across the top 7 cities, against approx. 1,30,170 units sold in Q1 2024. However, on a yearly basis, there has been a 5% rise in residential sales.
image001 (3)

The two western cities – MMR and Pune – accounted for over 52% of the total sales in the top 7 cities with over 62,685 units sold altogether in these cities in Q2 2024. NCR is the only city to see a quarterly rise (of 6%) in housing sales in the quarter against Q1 2024.

New launches across the top 7 cities continued to break previous records with a 6% Q-o-Q rise – from approx. 1,10,870 units in Q1 2024 to approx. 1,17,170 units in Q2 2024. MMR and Pune saw the maximum new supply, accounting for 54% of the total new launches across the top 7 cities. Individually, the two cities saw 31% and 1% quarterly increases in their new supply, respectively.

Notably, NCR witnessed a 134% Q-o-Q jump in new supply in Q2 2024 against Q1 2024.

Anuj Puri, Chairman – ANAROCK Group, says, “The quarterly decline seen in housing sales is essentially because of the all-time high base considered in the previous quarter, when more than 1.30 lakh units were sold. Most importantly, this drop is also due to the significant hike in property prices over the last one year, which in turn has prompted many investors to take a breather.”

Data indicates that average residential prices have seen a quarterly jump of 7% while annual rise of a significant 25% in the top 7 cities.

“NCR witnessed the highest quarterly jump of 10% in Q2 2024 while Hyderabad saw the highest yearly jump of 38% in average residential prices,” says Puri. “However, if prices are kept in check henceforth, housing sales may not be majorly impacted in the upcoming quarters.”

New Launch Overview

The top 7 cities recorded approx. 1,17,170 new units launched in Q2 2024, against approx. 1,10,870 units in Q1 2024 – increasing by 6% over the previous quarter. The key cities contributing to new launches in Q2 2024 were MMR (Mumbai Metropolitan Region), NCR, Pune, and Bengaluru, which together accounted for 82% of the supply addition.

  • MMR saw approx. 44,120 units launched in Q2 2024 – increasing by 31% over Q1 2024 and over 2% on yearly basis. More than 64% new supply was added in the sub-INR 80 lakh budget segment.
  • Pune added new supply of approx. 18,920 units in Q2 2024 compared to approx. 18,770 units in Q1 2024 – an increase of 1%. On a yearly basis, the city recorded a 11% decline in new supply. Over 73% of the new supply in Q2 2024 was added in the mid and premium segments (units priced between INR 40 lakh to INR 1.5 Cr.)
  • Hyderabad added approx. 13,750 units in Q2 2024, a quarterly decline of 40% but a 31% rise against the corresponding period in 2023. Over 69% of the new supply in Q2 2024 was added in the mid and premium price segments.
  • Bengaluru added approx. 16,020 units in Q2 2024, declining quarterly by 3%. On a yearly basis, there was 40% rise.  Approx. 83% of the new supply was added in the premium and luxury segments (INR 80 Lakh onwards) combined.
  • NCR saw a whopping 134% increase in new launches against Q1 2024, with approx. 17,030 units launched in Q2 2024. A whopping 82% of the new launches in second quarter this year were in the luxury segments priced >INR 1.5 Cr.
  • Chennai added approx. 5,180 units in Q2 2024, a quarterly decline of 29% against Q1 2024 and a yearly increase of 3% over Q2 2023. Over 93% was added in the mid and premium segments.
  • Kolkata added approx. 2,150 units in Q2 2024, a decrease of 50% over Q1 2024 and 13% drop against Q2 2023. Approx. 64% new supply was added in the mid segment priced between INR 40 lakh – INR 80 lakh.
City wise Supply (Units) and Q-o-Q Percentage Change
 Cities Name  Q2 2024  Q1 2024  % Change (Q1-2024 Vs Q2-2024)  Q2 2023  % Change (Q2-2023 Vs Q2-2024)
NCR 17,030 7,270 134% 8,461 101%
MMR 44,120 33,800 31% 43,393 2%
Bangalore 16,020 16,490 -3% 11,440 40%
Pune 18,920 18,770 1% 21,349 -11%
Hyderabad 13,750 22,960 -40% 10,468 31%
Chennai 5,180 7,290 -29% 5,035 3%
Kolkata 2,150 4,290 -50% 2,464 -13%
Total 1,17,170 1,10,870 6% 1,02,610 14%

Source: ANAROCK Research

Overall Sales Overview

Approx. 1,20,340 units were sold in Q2 2024 across the top 7 cities – a quarterly decline of 8% over Q1 2024. NCR, MMR, Bengaluru, Pune, and Hyderabad together accounted for 92% sales in the quarter. On a yearly basis, the top 7 cities recorded a 5% increase in housing sales with approx. 1,15,090 units sold back in Q2 2023.

  • NCR is the only city to see quarterly growth (of 6%) in housing sales among the top 7 cities – from approx. 15,650 units in Q1 2024 to approx. 16,550 units in Q2 2024.
  • MMR witnessed the maximum sales at approx. 41,540 units in Q2 2024, against approx. 42,920 units in Q1 2024 – declining by 3%.
  • Pune witnessed housing sales of 21,145 units in Q2 2024, decreasing by 8% over Q1 2024.
  • Bengaluru too saw housing sales decrease by 8% in Q2 2024 against Q1 2024, with approx. 16,360 units sold in the second quarter this year.
  • Chennai saw approx. 5,020 units sold in Q2 2024 – decreasing by 9% against Q1 2024.
  • Hyderabad recorded sales of approx. 15,085 units in Q2 2024, a drop of 23% over Q1 2024.
  • Kolkata saw housing sales decrease by 18% in the quarter against preceding quarter (Q1 2024); approx. 4,640 units were sold in Q2 2024.

City wise Absorption (In Units) and Q-o-Q percentage change

 Cities Name  Q2 2024  Q1 2024  % Change (Q1-2024 Vs Q2-2024)  Q2 2023  % Change (Q2-2023 Vs Q2-2024)
NCR 16,550 15,650 6% 16,450 1%
MMR 41,540 42,920 -3% 38,085 9%
Bangalore 16,360 17,790 -8% 15,045 9%
Pune 21,145 22,990 -8% 20,680 2%
Hyderabad 15,085 19,660 -23% 13,565 11%
Chennai 5,020 5,510 -9% 5,490 -9%
Kolkata 4,640 5,650 -18% 5,775 -20%
Total 1,20,340 1,30,170 -8% 1,15,090 5%

Unsold Housing Inventory – NCR Down 57%, South 11%, West 8% in 5 Years

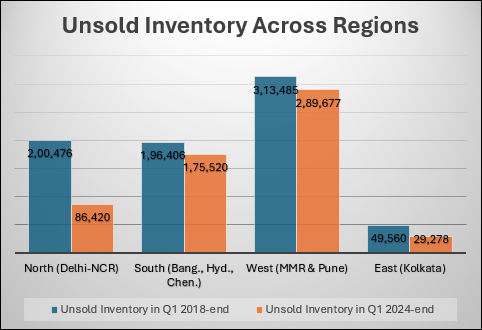
Mumbai, 24 May 2024: Going by a region’s prevailing unsold housing inventory as an indicator of its realty market’s health, North India’s Delhi-NCR – once notorious for speculation-driven oversupply and all-round market disarray – is in significantly better shape than the other regions. Latest ANAROCK data indicates that Delhi-NCR’s unsold inventory declined by a massive 57% in the last five years.

image002

The top Southern markets Bengaluru, Hyderabad, and Chennai saw their collective unsold stock shrink by 11% in this period. MMR and Pune in the West saw their cumulative unsold stock reduce by 8%. In the East, Kolkata saw its unsold inventory decline by an impressive 41% in the period.

NCR’s unsold stock declined from approx. 2 lakh units at Q1 2018-end to approx. 86,420 units by Q1 2024-end. In the same period, the main southern cities saw their unsold stock decline from over approx. 1.96 lakh units in Q1 2018 to over 1.76 lakh units in Q1 2024.

image001

Source: ANAROCK Research

South India’s relatively low decline of unsold inventory is attributable to a massive new launch rate in Hyderabad, most notably over the last two years. The city saw its housing stock almost quadruple in the last 5 years. Bengaluru saw unsold inventory decline by 50% in this period.

In the West, MMR and Pune saw unsold stock decline by 8% in the last five years – from approx. 3.13 lakh units in Q1 2018 to approx. 2.90 lakh units in Q1 2024.

Santhosh Kumar, Vice Chairman – ANAROCK Group, says, “What really worked for NCR market was developers’ determination to keep new supply addition under control. ANAROCK data indicates that NCR witnessed total new supply of approx. 1.81 lakh units between Q1 2018 to Q1 2024. In contrast, the southern and western markets saw significantly higher new supply additions of approx. 6.07 lakh units and 8.42 lakh units respectively.”

“NCR‘s upbeat performance also reflects renewed buyer confidence in the region,” says Santhosh Kumar. “RERA, GST and the intervention of AIFs like the SWAMIH fund have played a major role in this sentiment revival. As a result, more leading and listed players have increased supply in the region.”

Zone New Supply Added in last 5 Yrs. (Units)
North 1,80,885
South 6,06,654
West 8,42,298
East 80,934

Source: ANAROCK Research

Of the total unsold inventory in NCR:

  • Gurgaon currently has the maximum stock of approx. 33,326 units – a 37% decrease in the last five years.
  • Greater Noida is next with approx. 18,668 units lying unsold as of Q1 2024-end. However, Greater Noida reduced its stock by a whopping 70% since Q1 2018.
  • Ghaziabad saw its unsold stock decline to approx. 11,011 units in Q1 2024, from approx. 37,005 units in Q1 2018 – a massive 70% 5-year decline.
  • Noida had approx. 7,451 unsold units by Q1 2024-end, against 25,669 units in same quarter of 2018 – thus declining by 71%.
  • Delhi, Faridabad & Bhiwadi together had approx. 15,964 unsold units as on Q1 2024-end, from approx. 23,038 units at Q1 2018-end – a 31% decrease.
Available Inventory in Delhi-NCR (Units)
  Q1 2018-end Q1 2024-end % Change
Gurgaon 53,136 33,326 -37%
Noida 25,669 7,451 -71%
Greater Noida 61,628 18,668 -70%
Ghaziabad 37,005 11,011 -70%
Faridabad, Delhi, Bhiwadi 23,038 15,964 -31%
Total 2,00,476 86,420 -57%

Source: ANAROCK Research

General Elections – Will the Housing Market Create Another Peak in 2024

Mumbai 21 March 2024: General elections and residential real estate appear closely linked – at least, that is what the previous two election years’ data trends indicate. 2014 and 2019, both election years, saw housing sales create new peaks. In 2014, sales in the top 7 cities scaled up to approx. 3.45 lakh units while new launches were the highest ever at nearly 5.45 lakh units.

Anuj Puri, Chairman - ANAROCK Group
Anuj Puri, Chairman – ANAROCK

Likewise, in 2019, housing sales scaled up to approx. 2.61 lakh units while new launches increased to approx. 2.37 lakh units after a lull in the residential real estate market between 2016 and 2019. Major structural reforms like DeMo, RERA, and GST, introduced in 2016 and 2017, transitioned Indian real estate from something of a Wild West frontier market to more organised and regulated.

Most fly-by-night developers have exited the market since then and organised players have emerged in strength, significantly reviving confidence among homebuyers.

Anuj Puri, Chairman – ANAROCK Group, says, “A major factor driving the housing market’s phenomenal performance in 2014 and 2019 would have been the decisive election results. For homebuyers, it was an end to fence-sitting and a confident move to ‘buy’ positions.”

On examining the price trends in these election years, it emerges that 2014 was a better year than 2019. ANAROCK data indicates that in 2014, the average prices in the top 7 cities rose by over 6% annually against the preceding year – from INR 4,895 per sq. ft. in 2013 to INR 5,168 per sq. ft. in 2014. As for 2019, average prices rose by merely 1% annually – from INR 5,551 per sq. ft. in 2018 to INR 5,588 per sq. ft. in 2019.

India’s residential real estate sector witnessed a major slowdown between 2016 to 2019. The major market shake-up brought on by policy reforms between 2016 and 2017 was followed by the NBFC crisis post the IL&FS issue in 2018. This caused considerable turmoil in the residential real estate industry.

From 2019 onwards, the first green shoots of revival were temporarily dampened by the pandemic in early 2020. Thereafter, against all expectations, the housing market went into overdrive from 2021 onwards and the momentum continues till date.

How will the current election year (2024) pan out for the Indian housing market?

“As things stand now, all signs currently favour the residential market in 2024, and the year can well create another peak in housing sales and new launches,” says Puri. “Housing demand continues to be upbeat across cities after the announcement of the election dates, with homebuyers remaining highly optimistic about the real estate market.”

Factors Favouring a New Peak in 2024:

  • Most real estate regulatory reforms and norms are already in place, and the worst of the shake-up is behind us.
  • International organizations like IMF have strong GDP growth predictions for India for the next few years. The Indian economy is growing rapidly, and this indirectly has a positive impact on the real estate market.
  • Inflation is currently well under control, bolstering financial optimism and confidence among homebuyers.
  • Based on growing homebuyer demand, developers have closed substantial land deals in the last one year, and most of their balance sheets are clean. Many large developers with good track records and solid balance sheets are venturing into newer territories to increase their presence.

Grade A Developer Dominance Fuels 40% Sale of New Launch Supply in 7 Cities in 2023

Mumbai, 29 February 2024: The ever-increasing dominance of branded developers in Indian residential real estate is shifting homebuyer attention from ready-to-move or almost-complete projects to newly launched projects. Latest ANAROCK Research data shows that over 40% of approx. 4.77 lakh homes sold in 2023 was in newly launched projects. The share of newly launched supply sales in pre-pandemic 2019 was much lower at 26% of approx. 2.61 lakh homes sold that year.
  • In 2020, of approx. 1.38 lakh units sold in the top 7 cities, 28% were launched during the year
  • In 2021, 34% of approx. 2.37 lakh units sold in the top 7 cities were new launches
  • In 2022, out of approx. 3.65 lakh units sold, 36% were new launches
Among the top 7 cities, NCR saw the lowest absorption of newly launched homes – of 65,625 units sold in 2023, about 27% were launched during the year. The remaining units were sold in projects launched before 2023. Interestingly, Gurugram outperformed other markets in the NCR region – of 36,970 units sold in Millennium City in 2023, at least 35% were newly launched.
Anuj Puri, Chairman - ANAROCK Group
Anuj Puri, Chairman – ANAROCK Group
   Anuj Puri, Chairman – ANAROCK Group, says, “The fact that 40% of newly launched housing stock has already been sold across the top cities strongly underscores increasing homebuyer confidence on new projects. Ready homes became the biggest draw amid project delays in the past, but the trend is now changing. This is attributable to the increasing market share of financially strong branded developers with sound completion track records in the last 2-3 years.”
An increasing number of homebuyers are reposing their faith in these players, and newly launched projects are steadily gaining traction. These players have recorded very healthy sales since the pandemic, thanks to a stronger focus on market research.
“Also, in contrast to earlier years, developers are launching projects that dovetail with actual demand,” says Puri. “Their focus on good locations and appropriate unit sizes and configurations is very obvious. Several leading developers are snapping up land parcels across key cities to develop residential projects that are aligned with what customers want. ANAROCK data indicates that there were at least 97 separate land deals for over 2,707 acres closed in 2023 across the country, with at least 72% of the sold land earmarked for residential development.”
The NCR real estate market has seen a complete transformation from previous times; nevertheless, a residual hesitancy towards under-construction homes in the region is a reminder of its years of oversupply and speculative pricing.
“With developers now carefully analysing and calibrating supply and ticket sizes, we are unlikely to see mistakes from the past being repeated,” adds Puri. “Markets like Gurugram are seeing stellar performances by branded players, with projects being sold out within a short time of their launch.”
City-wise Absorption Trends
At 27%, NCR saw the lowest sales share of newly launched units in 2023. Gurugram has outperformed other key markets within the NCR with new supply seeing significant sales. Other cities with a low fresh supply absorption share include Kolkata and MMR at 30% and 36%, respectively.
2023
2019
City
% Share of New Launch Absorption
NCR
27%
22%
MMR
36%
23%
Bangalore
51%
27%
Pune
41%
34%
Hyderabad
50%
28%
Chennai
58%
28%
Kolkata
30%
23%
Total
40%
26%
Source: ANAROCK Research
  • In MMR, of 1,53,870 units sold in 2023, approx. 36% were new launches. In 2019, of 80,870 units sold, 23% were in new units
  • In NCR, of 65,625 units sold in 2023, approx. 27% were launched in the same year. In 2019, of 46,920 units sold, the sales share of newly launched units was 22%.
  • In Chennai, of 21,630 units sold in 2023, newly launched units accounted for a healthy 58% share – up from 28% of 11,820 units sold in 2019.
  • In Kolkata, of 23,030 units sold in 2023, about 30% were newly launched. In 2019, approx. 13,930 units were sold, of which 23% sales were of newly launched units.
  • In Bengaluru, of 63,980 units sold in 2023, the sale share of newly launched units was 51% – up from 27% of 50,450 units in 2019.
  • In Pune, of 86,680 units sold in 2023, the sale share of newly launched units was 41% – up from 34% of 40,790 units in 2019.
  • In Hyderabad, of approx. 61,715 units sold in 2023, approx. 50% were launched in the same year – significantly up from 28% of approx. 16,590 units in 2019.