India’s edtech industry is learning an important business lesson: attracting millions of students is only the beginning; retaining their trust and delivering meaningful results are what make a business sustainable.
During the COVID-19 pandemic, online education moved from an alternative to a necessity. School closures, competitive examination preparation and the growing need for digital skills created unprecedented demand for online learning platforms. Investors poured money into the sector, while companies expanded rapidly to capture a market that appeared capable of growing almost indefinitely.
That momentum has since given way to a more measured environment. As classrooms reopened and families reassessed their spending, edtech businesses faced questions about course prices, learning outcomes and the long-term value of digital subscriptions. Funding became harder to secure for companies unable to demonstrate a clear path to profitability.
Yet the sector’s growth story is far from over. India’s large student population, demand for competitive examination coaching and need for workforce training continue to create opportunities. The difference is that businesses must now demonstrate how they can turn these opportunities into reliable revenue without compromising educational quality.
Market Growth Remains Strong, but Business Priorities Are Changing
India’s edtech market has been estimated at around $7.5 billion, with projections suggesting it could reach approximately $29 billion by 2030. These figures are estimates rather than guaranteed outcomes, and market valuations can differ depending on which education services are included.
Nevertheless, the projected expansion points to considerable commercial potential. Online tutoring, examination preparation, professional upskilling and digital learning resources are serving different groups of students and working professionals.
The scale of India’s education system provides an important foundation for this demand. According to the Ministry of Education’s Unified District Information System for Education Plus data for 2023–24, India had approximately 24.8 crore school students across about 14.7 lakh schools. Reaching even a small proportion of this population with useful digital learning services represents a significant opportunity.
However, a large addressable market does not guarantee that every platform will succeed. Students and parents increasingly expect courses to justify their cost through better teaching, accessible content and visible progress. Companies that depend heavily on advertising or aggressive enrolment targets may find it difficult to build lasting customer relationships.
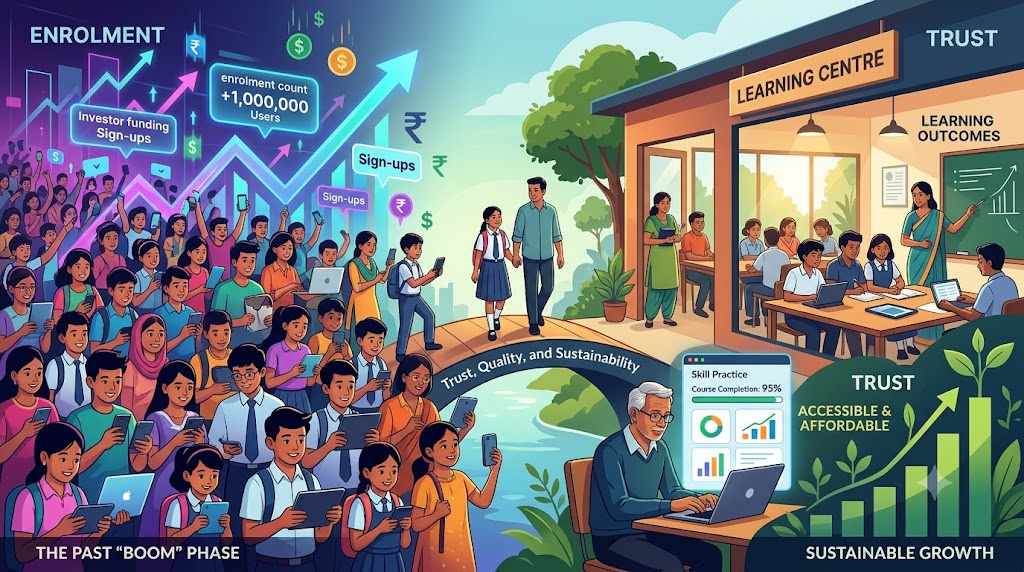
The focus is consequently shifting from acquiring as many users as possible to serving learners more effectively.
The Pandemic Boom Exposed the Risks of Rapid Expansion
The pandemic created ideal conditions for digital education businesses. With physical classrooms unavailable, online platforms became a lifeline for students preparing for examinations and families trying to maintain learning at home.
Investor interest rose sharply. Industry estimates place edtech funding in India at roughly $4 billion or more in 2021, although totals vary by source and methodology. The funding supported hiring, technology development, acquisitions, marketing and expansion into new education categories.
But the rush to grow also encouraged expensive business practices. Some companies invested heavily in advertising, sales operations and customer acquisition, assuming that rising enrolments would eventually translate into strong profits.
When in-person education resumed, those assumptions came under pressure. Students returned to schools and coaching centres, while parents reconsidered the need to pay for multiple digital services. Businesses with high operating expenses and weak customer retention faced difficult decisions about staffing, spending and expansion.
The experience revealed a fundamental weakness in the growth-at-all-costs approach. Rapid revenue growth can conceal financial problems when the cost of acquiring and serving each customer remains too high.
For the industry, the lesson is clear: growth must be supported by sound unit economics, repeat demand and a credible route to profitability.
Profitability Is Becoming More Important Than Enrolment Numbers
Edtech companies are increasingly under pressure to show that their business models can sustain themselves without continuous fundraising. This is changing decisions about course pricing, marketing expenditure, product development and expansion.
Instead of launching numerous products to attract different audiences, companies may benefit from concentrating on areas where they have strong teaching capabilities and a clear understanding of student needs.
Customer retention is particularly important. A student who completes a course, sees genuine improvement and returns for another programme can provide more sustainable value than a customer attracted through a discount but unlikely to renew.
Businesses can also improve their financial performance by using better demand forecasting, reducing unnecessary spending and developing content that can be reused without sacrificing teaching quality.
This does not mean that cost-cutting alone will guarantee success. Excessive reductions in teacher support, counselling or customer service can weaken the learning experience. Sustainable growth requires businesses to control expenses while protecting the elements that make their services useful.
Hybrid Learning Offers a More Practical Business Model
The pandemic demonstrated that digital platforms can make education accessible across geographical boundaries. However, it also showed that online learning does not work equally well for every student.
Some learners benefit from recorded lessons and flexible schedules, while others need classroom interaction, regular supervision and direct access to teachers. This has created opportunities for hybrid models that combine digital resources with physical teaching and mentoring.
For example, students can use online lessons for revision and practice while attending local centres for doubt-clearing sessions, assessments and structured study. Such arrangements may appeal to families seeking the flexibility of technology without losing personal guidance.
Hybrid education can also help businesses reach smaller cities and towns, where demand for specialised instruction may exist but access to experienced teachers is limited.
However, physical centres bring additional costs, including rent, staffing and administration. Companies must carefully assess local demand before expanding their offline presence. The most effective model will depend on the subject, learner profile and affordability of the service.
Affordability Will Determine How Far EdTech Can Expand
India’s education market includes families with very different financial circumstances and levels of digital access. While some can afford premium coaching subscriptions, others must carefully balance educational expenses against household budgets.
This creates an opportunity for platforms that offer reasonably priced courses, regional-language instruction and flexible payment options. Free introductory lessons, low-cost practice material and affordable subscriptions can help students explore learning opportunities without making a large financial commitment.
Access to technology remains important. According to the National Sample Survey’s Household Consumption Expenditure Survey 2023–24, average monthly per-capita consumption expenditure was estimated at ₹4,122 in rural India and ₹6,996 in urban India, excluding the imputed value of items received free through social welfare programmes. The figures illustrate the differences in household spending capacity and why education pricing must reflect affordability.
A digital course that is technically available to everyone is not necessarily accessible to everyone. Device availability, internet connectivity, language and the ability to study in a suitable environment can all affect participation.
Companies that address these barriers can expand their customer base while contributing to more inclusive access to education.
Artificial Intelligence Creates New Opportunities for EdTech Businesses
Artificial intelligence is opening another chapter for the sector. AI-supported learning tools can explain concepts, generate practice questions, provide feedback and help students identify subjects that require additional attention.
For teachers, these tools may reduce time spent on repetitive tasks, allowing greater attention to individual learning needs. For businesses, AI can support personalised learning experiences and help develop content for different skill levels.
However, the technology must be used carefully. Automated systems can provide incorrect explanations, and students may struggle to distinguish reliable guidance from inaccurate answers. Younger learners also require appropriate supervision and safeguards for their personal information.
AI adoption should therefore be judged by whether it improves understanding, engagement and learning outcomes, not simply by whether a platform has introduced a new feature.
Companies that combine technology with qualified teachers, structured lessons and reliable assessment may be better placed to build long-term credibility.
Trust and Measurable Results Will Shape the Next Winners
As the market matures, parents and students are likely to pay closer attention to what they receive for their money. Clear pricing, transparent course conditions and realistic claims about examination results or career prospects can help businesses build stronger relationships with customers.
Learning outcomes also need greater attention. Enrolment figures and app downloads may indicate popularity, but they do not necessarily show whether students understand a subject or complete a course.
Platforms can develop more meaningful measures by tracking course completion, student progress, assessment performance and learner satisfaction. Transparent feedback and responsive support can further help identify weaknesses in the learning experience.
For investors, these indicators can provide a better picture of whether a company has built a durable business rather than one dependent on promotional spending.
For students and parents, they offer a more practical basis for choosing a course.
The Road Ahead for India’s EdTech Industry
India’s edtech industry is moving beyond the extraordinary circumstances that fuelled its pandemic-era expansion. The sector still has considerable potential across school education, examination preparation, professional training and lifelong learning, but future growth will depend on more than technology and funding.
Businesses will need to balance financial discipline with accessible pricing, effective teaching and responsible innovation. Hybrid learning, regional-language content and carefully implemented AI tools can create new opportunities, provided they address genuine learner needs.
The next phase will favour companies that understand education as a long-term relationship rather than a one-time sale. By focusing on student progress, customer trust and sustainable operations, edtech businesses can build stronger foundations for growth.
India’s digital education opportunity remains significant. Its lasting success, however, will be measured not by the amount of money raised or the number of students enrolled, but by how effectively technology helps people learn, develop skills and improve their future prospects.